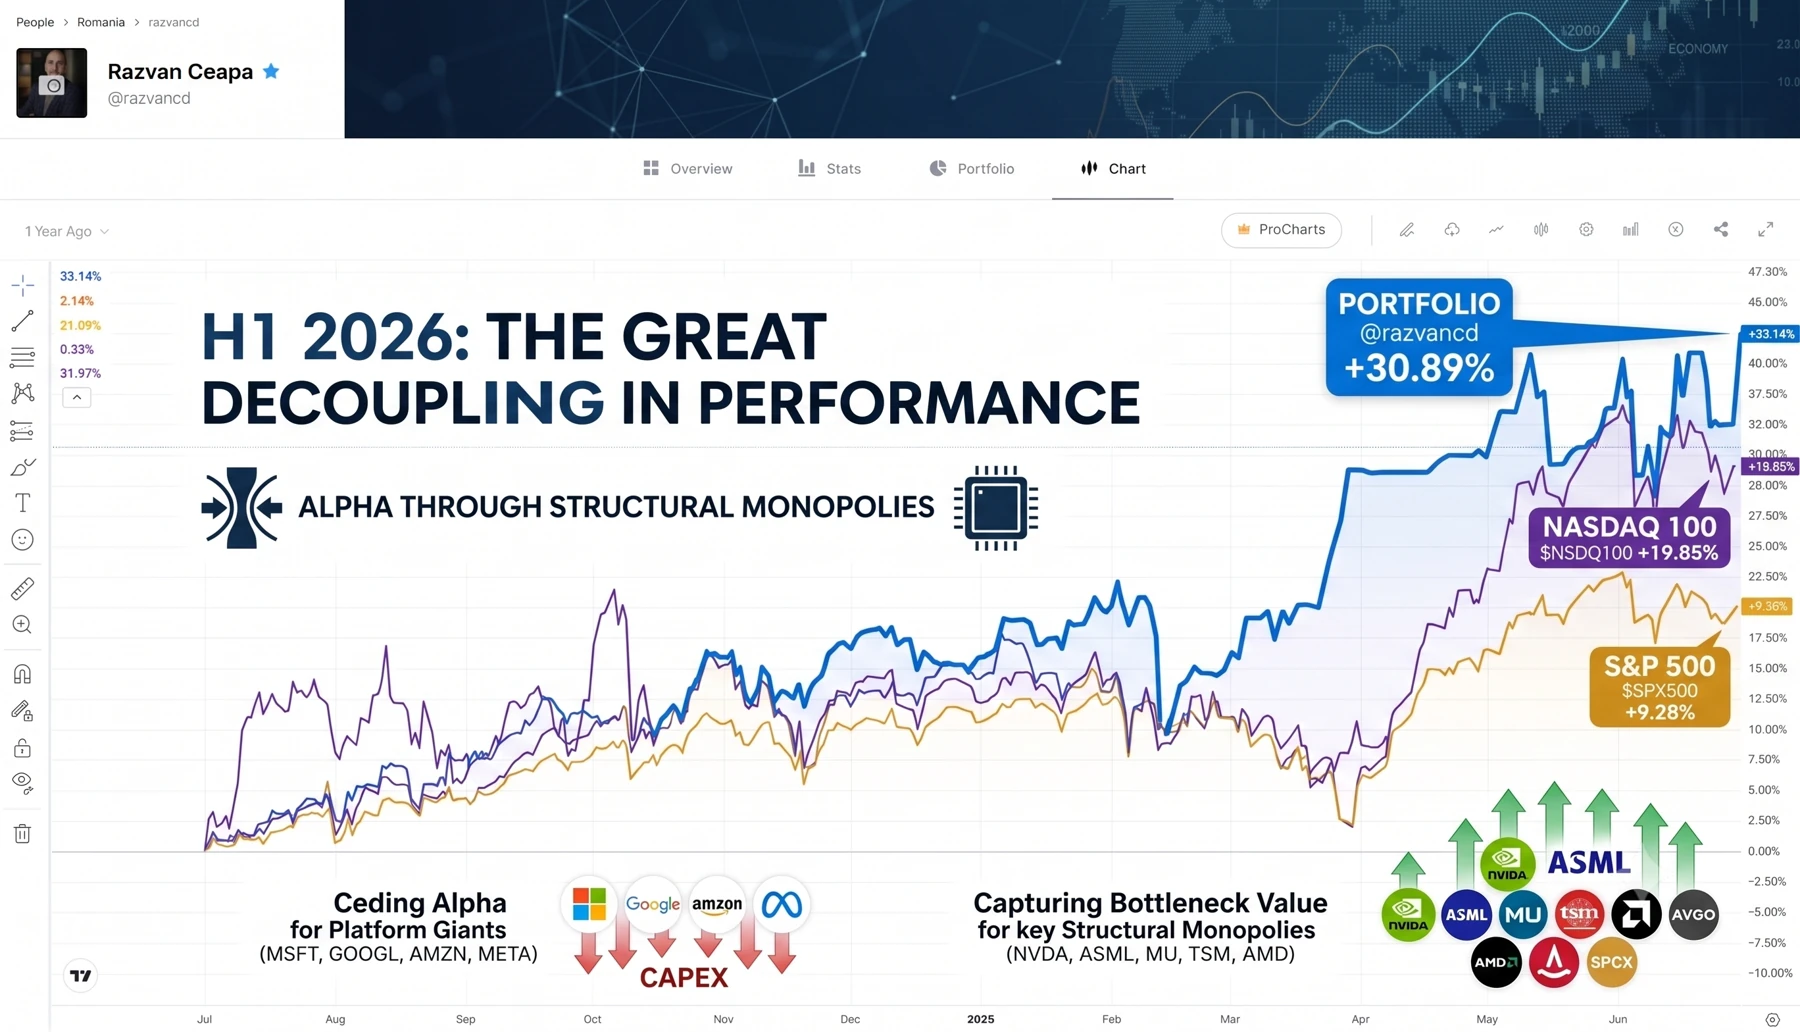
📊 𝗧𝗵𝗲 𝗚𝗿𝗲𝗮𝘁 𝗗𝗲𝗰𝗼𝘂𝗽𝗹𝗶𝗻𝗴: 𝗛𝟭 𝗣𝗲𝗿𝗳𝗼𝗿𝗺𝗮𝗻𝗰𝗲 𝗥𝗲𝗽𝗼𝗿𝘁 (+𝟯𝟬.𝟴𝟵%)
The first half of the year (H1) has provided a definitive "proof of concept" for my updated investment thesis: The Economics of Chokepoints.
While the broader markets showed resilience, we have successfully decoupled from the benchmarks by moving up the capital food chain. In an era defined by a trillion-dollar AI arms race, the most significant alpha is no longer found in the platform giants, but in the Structural Monopolies that function as the digital world’s toll booths.
𝗧𝗵𝗲 𝗛𝟭 𝗗𝗲𝗹𝘁𝗮 (𝗠𝗮𝘁𝗵𝗲𝗺𝗮𝘁𝗶𝗰𝗮𝗹 𝗣𝗿𝗼𝗼𝗳)
Our performance reflects a rigorous concentration of capital in high-conviction bottlenecks:
• $SPX500 (S&P 500) H1: +𝟵.𝟮𝟴%
• $NSDQ100 (Nasdaq 100) H1: +𝟭𝟵.𝟴𝟱%
• 𝗢𝘂𝗿 𝗣𝗼𝗿𝘁𝗳𝗼𝗹𝗶𝗼 𝗛𝟭: +𝟯𝟬.𝟴𝟵%
𝗦𝘁𝗿𝗮𝘁𝗲𝗴𝗶𝗰 𝗔𝗻𝗮𝗹𝘆𝘀𝗶𝘀: 𝗪𝗵𝘆 𝘁𝗵𝗲 𝗣𝗹𝗮𝘁𝗳𝗼𝗿𝗺 𝗚𝗶𝗮𝗻𝘁𝘀 𝗮𝗿𝗲 𝗖𝗲𝗱𝗶𝗻𝗴 𝗔𝗹𝗽𝗵𝗮
For a decade, owning $MSFT, $GOOGL, $AMZN, and $META was the default winning strategy. However, a fundamental shift in the capital stack is occurring. We are transitioning from Platform Dominance to Compute/Physical Dominance.
𝟭. 𝗧𝗵𝗲 𝗖𝗔𝗣𝗘𝗫 𝗧𝗿𝗮𝗽: The "Big Tech" giants are currently forced into a multi-trillion dollar Capex race to maintain relevance. In economic terms, they have become the "Customers" of the new era. Every dollar they spend on infrastructure leaves their balance sheet and lands on the top line of the companies I call Chokepoint Assets.
𝟮. 𝗩𝗮𝗹𝘂𝗲 𝗖𝗮𝗽𝘁𝘂𝗿𝗲 𝗮𝘁 𝘁𝗵𝗲 𝗕𝗼𝘁𝘁𝗹𝗲𝗻𝗲𝗰𝗸: Marginal returns are hitting mature software businesses. Meanwhile, the companies controlling the physical chokepoints—lithography, logic, and high-bandwidth memory—are experiencing explosive, non-linear growth.
𝗢𝘂𝗿 𝗖𝗼𝗿𝗲 𝗖𝗼𝗻𝗰𝗲𝗻𝘁𝗿𝗮𝘁𝗶𝗼𝗻 𝗳𝗼𝗿 𝗛𝟮
To capture this alpha, I have recently optimized the portfolio (notably in mid-June) to lean further into these structural monopolies:
• 𝗦𝗲𝗺𝗶𝗰𝗼𝗻𝗱𝘂𝗰𝘁𝗼𝗿 𝗟𝗶𝘁𝗵𝗼𝗴𝗿𝗮𝗽𝗵𝘆: $ASML (ASML Holding NV) — The only entity capable of producing the future.
• 𝗧𝗵𝗲 𝗠𝗲𝗺𝗼𝗿𝘆 𝗢𝗹𝗶𝗴𝗼𝗽𝗼𝗹𝘆: $MU (Micron Technology, Inc.) — Solving the physical GPU bottleneck.
• 𝗖𝗼𝗺𝗽𝘂𝘁𝗲 & 𝗡𝗲𝘁𝘄𝗼𝗿𝗸𝗶𝗻𝗴: $NVDA (NVIDIA Corporation), $AMD (Advanced Micro Devices Inc), and $AVGO (Broadcom Inc).
• 𝗙𝗼𝘂𝗻𝗱𝗮𝘁𝗶𝗼𝗻𝗮𝗹 𝗜𝗻𝗳𝗿𝗮𝘀𝘁𝗿𝘂𝗰𝘁𝘂𝗿𝗲: $TSM (Taiwan Semiconductor) and the orbital infrastructure of $SPCX (SpaceX).
𝗟𝗼𝗼𝗸𝗶𝗻𝗴 𝗔𝗵𝗲𝗮𝗱
We do not chase broad market beta. We do not over-diversify to hide from volatility. Our 2-year performance (+116.49%) and our vs. Last Year results (+42.35%) confirm that a disciplined, analytical approach to supply chain dominance consistently outperforms blind index-tracking.
For investors seeking a high-alpha, professionally managed exposure to the builders of the digital future—rather than just the users of it—I invite you to review my open positions and historical data.
#Investing #H1Results #MacroStrategy #AI #PortfolioAnalysis #StructuralMonopolies