Titlu: The ASML Paradox: Record Orders, Red Candle. Why? 📉📈
Today, the market behavior around ASML provided a textbook example of "complexity risk."
On the surface, the numbers were stellar. Beneath the surface, the market found reasons to sell.
Here is the full breakdown of the Q4 report—the Good, the Bad, and the Strategic Verdict.
1. The Headline: A Monster Beat on Demand
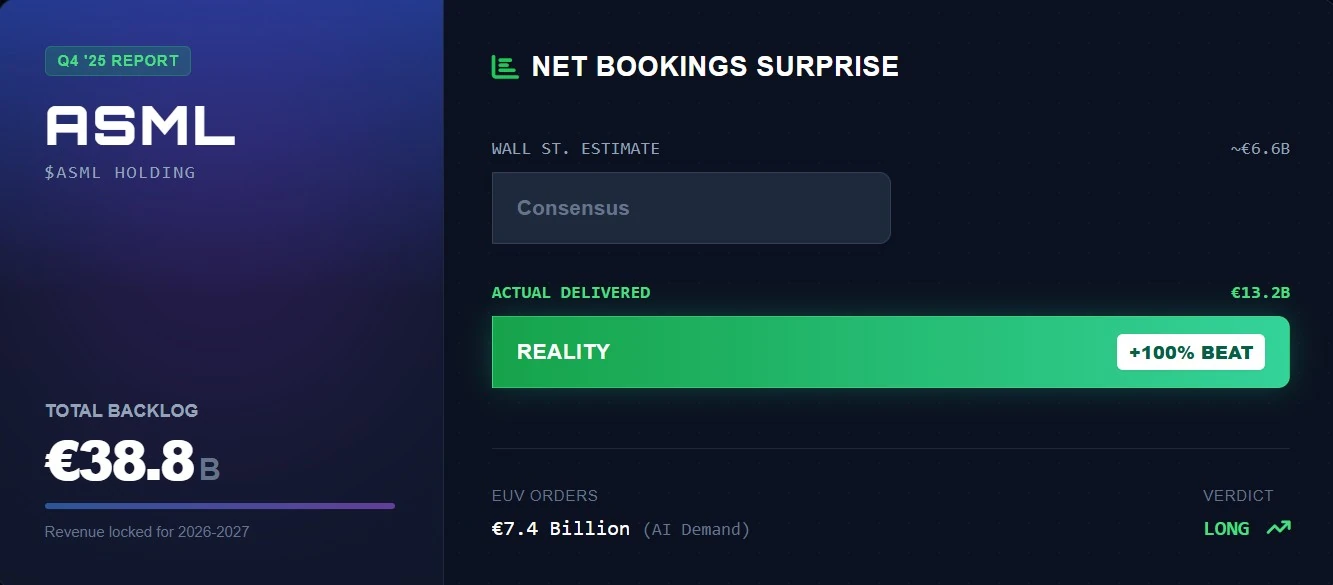
Wall Street consensus for net bookings was ~€6.6B.
ASML delivered €13.2B.
This is a 100% beat. The AI infrastructure build-out (TSMC, Samsung, Intel) is not slowing down; it is accelerating violently. €7.4B of these orders were for EUV systems alone. The backlog is now at a record €38.8B, securing revenue well into 2027.
2. The Context: Why the Stock Sold Off?
If demand is so high, why did the price fade intraday? Three critical factors spooked the algorithms:
The China De-risking: Management indicated a sharp normalization of China's share in the revenue mix (dropping towards ~20%). While algorithms see this as "lost revenue," long-term investors should see this as "de-risking." The company is becoming less vulnerable to future geopolitical bans.
DUV Plateau: Sales for older DUV (Deep Ultraviolet) tech are stagnating. The growth engine is now exclusively advanced EUV.
Margin Compression: Guidance for 2025 Gross Margins remained conservative (51-53%). Why? Because ramping up the new "High-NA" machines is expensive. ASML is sacrificing short-term efficiency for long-term monopoly dominance.
3. The Verdict
The "sell-off" today is technical positioning and profit-taking after a +30% run-up in January.
Fundamentally, the thesis is stronger today than yesterday.
The "China risk" is fading. The "AI Demand" is confirmed by cash deposits.
Volatility is the price you pay for owning the most important company in the semiconductor supply chain. I am holding.
$ASML $TSM $NVDA $SOXX