Return is Vanity. Risk-Adjusted Return is Sanity. 📊
Anyone can make money in a bull market by using leverage.
But can you generate "Alpha" without reckless downside risk?
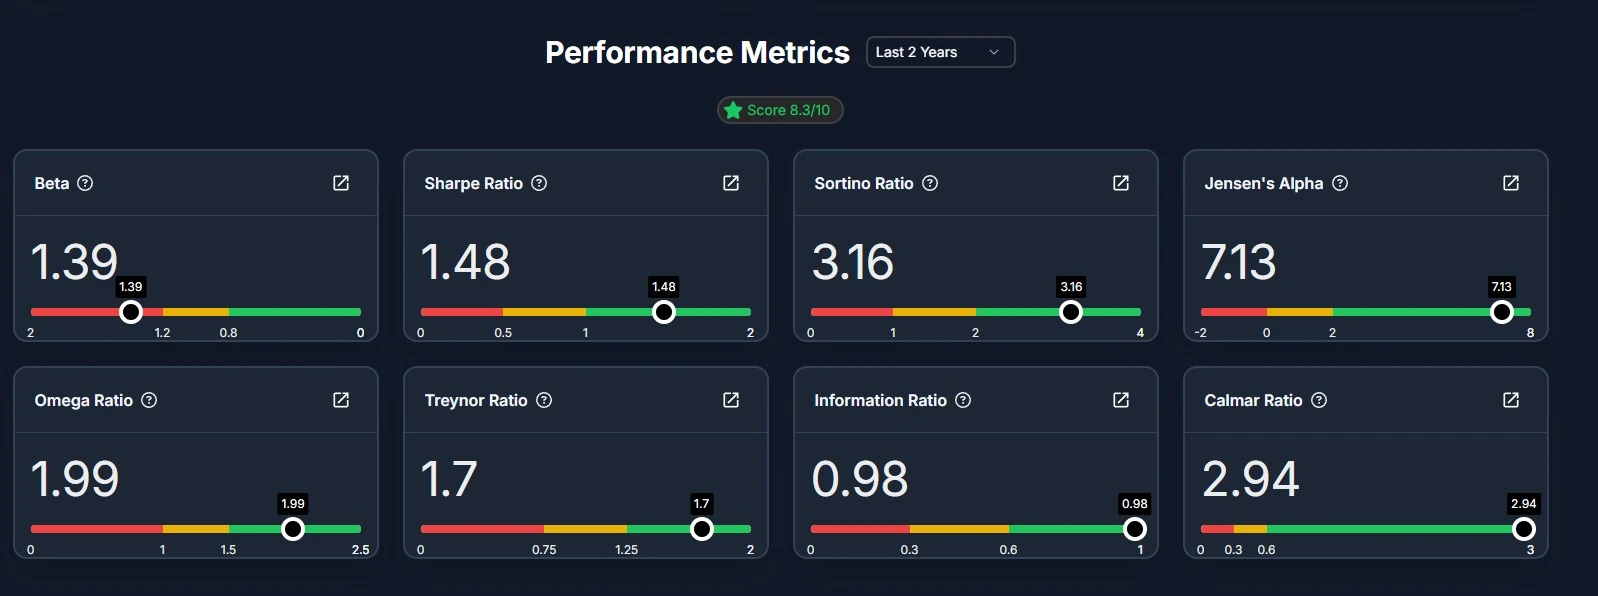
Attached is the official eToro risk audit of my strategy for the last 2 years.
1. The Skill Metric: Jensen's Alpha (7.13)
This is the most important number on the board.
A score > 0 means you beat the benchmark after adjusting for risk.
A score of 7.13 implies significant value added through stock selection. We aren't just riding the index; we are actively outperforming it.
2. The Discipline Metric: Sortino Ratio (3.16)
Unlike the Sharpe Ratio (which punishes all volatility), Sortino only punishes downside volatility.
A ratio above 3.0 is elite. It means that when our portfolio moves fast, it usually moves up.
3. The Aggression Metric: Beta (1.39)
We are 39% more volatile than the S&P 500. I accept this.
Volatility is the price of admission for superior returns. As long as the Alpha is high, the Beta is justified.
We don't just chase returns. We engineer them.
$NVDA $ASML $MSFT $SPX500 $NSDQ100