Blogger edition published 10 October 2026 · Source updated 10 October 2026. Original publication dates are preserved; the website import date is not used.
Historical article. Figures, holdings and views reflect the original publication, not current conditions. Claims are preserved, not independently revalidated. Capital at risk.
September 2026 Portfolio Review: Yields, CapEx, and Structural Monopolies
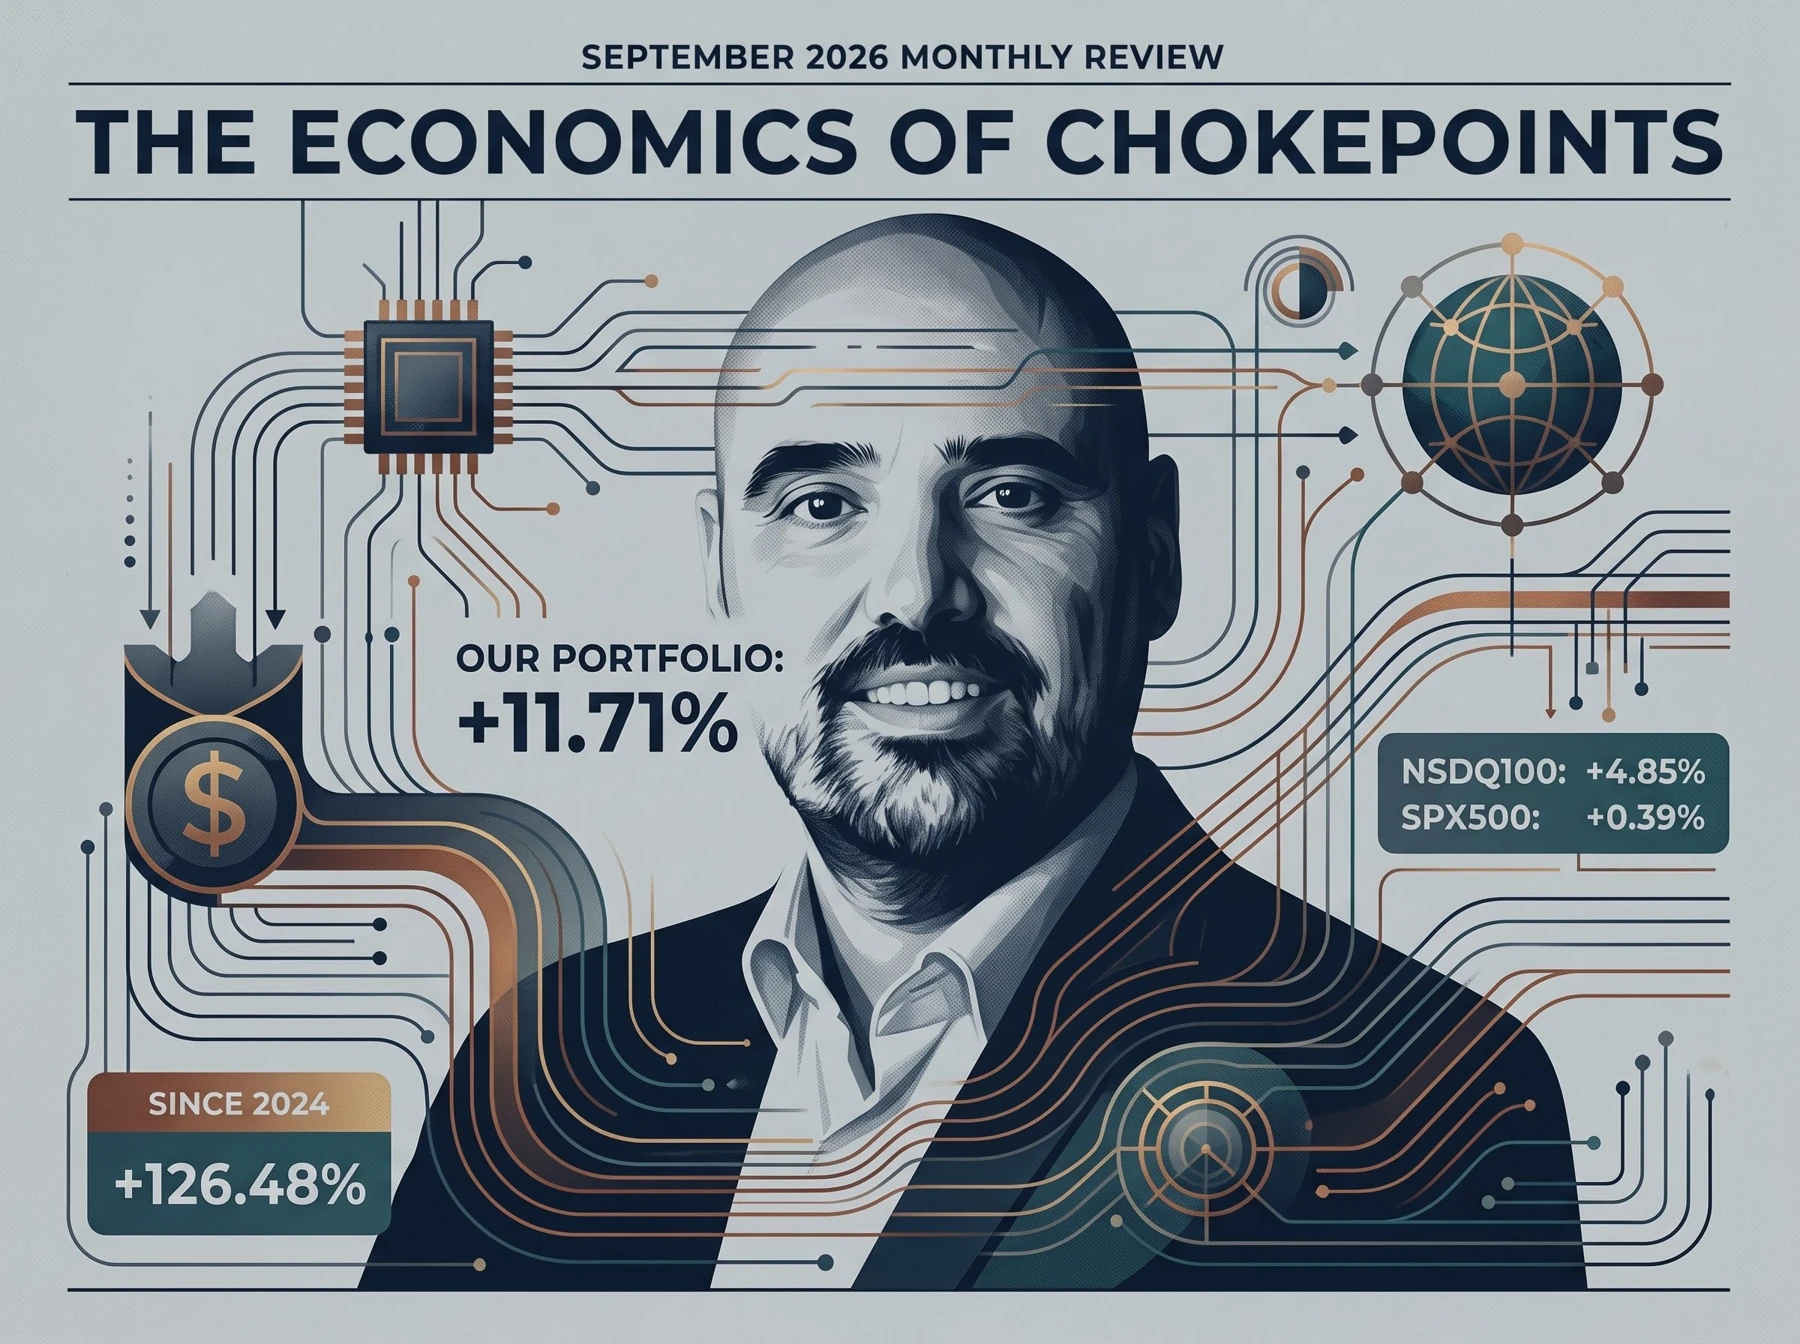
Our portfolio closed September 2026 with an +11.71% return, decisively decoupling from the S&P 500 (+0.39%) and the Nasdaq 100 (+4.85%). Total performance since January 2024 stands at +126.48%.
This outperformance occurred during a period of severe macroeconomic tightening. The Federal Reserve executed a 25-basis-point rate hike, elevating the target range to 3.75%–4.00%. Concurrently, the 10-year US Treasury yield breached the 5% threshold. Traditional financial models mandate that rising borrowing costs compress equity multiples, which is exactly why broad indices stalled. The financial media quickly amplified an "AI slowdown" narrative, triggering a temporary pullback across standard semiconductor index funds.
Our capital allocation bypassed this margin compression entirely due to the mechanics of our structural monopoly thesis:
Absolute Pricing Power: We do not own broad technology ETFs. We own the physical supply chain bottlenecks (NVIDIA, ASML, TSMC). These entities do not absorb higher macroeconomic costs; they pass them directly downstream.
CapEx Inelasticity: Hyperscalers (Microsoft, Amazon, Alphabet) cannot reduce their infrastructure investments without forfeiting their platform moats. The hardware compute layer functions as a closed-loop economic system. Even with a 5% risk-free rate, they are mathematically forced to procure hardware.
Immunity to the Cost of Capital: When the 10-year yield spikes, consumer-facing technology companies struggle with demand destruction. Structural monopolies are bounded strictly by physical supply constraints, not macroeconomic demand cycles.
Volatility is a statistical feature of concentrated alpha, not a bug. We continue to ignore short-term interest rate noise and concentrate capital aggressively in the physical infrastructure of the digital economy.
Copier Blueprint
I manage this strategy openly as a Popular Investor on eToro.
Search for razvancd.
Click Copy and strictly check "Copy Open Trades" to capture our exact 16-position allocation.
Minimum recommended allocation: $500.Copy Trading is not investment advice | Capital at risk | Past performance does not guarantee future results.
eToro version · 5 October 2026
This published adaptation is preserved in full alongside the Blogger article.
September 2026 Portfolio Review: Yields, CapEx, and Structural Monopolies
In September, our portfolio generated a return of +11.71%, decisively outperforming both the $NSDQ100 (+4.85%) and the $SPX500 (+0.39%).
The macroeconomic environment this month tested broad market valuations. The Federal Reserve, under Chair Kevin Warsh, executed a 25 bps rate hike, pushing the target range to 3.75%-4.00% in response to sticky core PCE inflation. Concurrently, the 10-year Treasury yield temporarily breached the 5% threshold. This tightening of financial conditions triggered an expected equity volatility spike and a broader market narrative of an "AI slowdown," driving a temporary pullback in standard semiconductor indices.
Broad indices struggled because they are overexposed to companies facing margin compression from higher borrowing costs. Our portfolio decoupled from this beta drag due to our strict concentration in structural monopolies.
Our outperformance is a direct mathematical result of "The Economics of Chokepoints" thesis:
• Absolute Pricing Power: We don't hold broad tech exposure. We own the supply chain bottlenecks ($NVDA, $ASML, $TSM). These entities dictate terms to the market.
• CapEx Inelasticity: Hyper-scalers cannot reduce their infrastructure investments without losing their competitive moat, regardless of the Fed's rate path. The hardware layer remains a closed-loop economic system.
• Immunity to Cost of Capital: When the 10-year yield spikes, consumer-facing tech struggles. Structural monopolies don't. Their growth is bounded by physical supply constraints, not macroeconomic demand cycles.
Volatility is a statistical feature of the market, not a bug. We continue to ignore short-term macroeconomic noise to focus aggressively on the entities building the physical infrastructure of the digital economy. Our capital allocation remains disciplined, data-driven, and highly concentrated, yielding a +126.48% return over 2 years.
Copy Trading is not investment advice | Capital at risk | Past performance does not guarantee future results. Full disclosures.