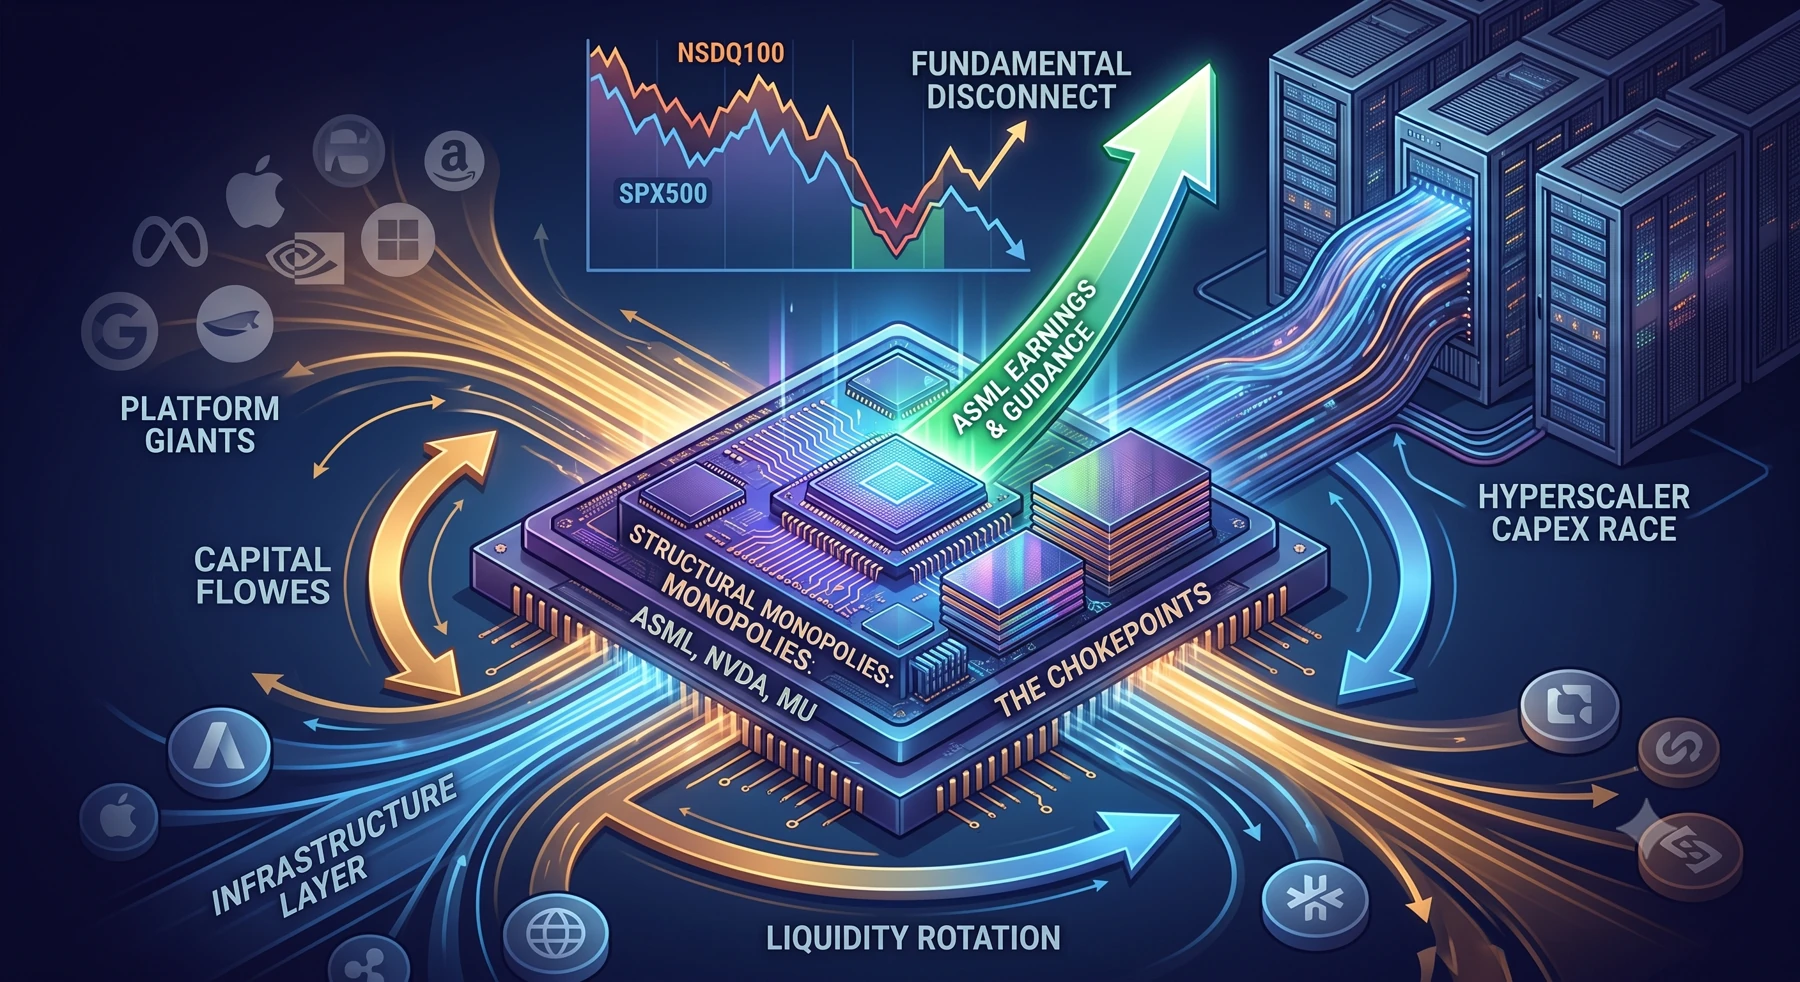
📊 𝗠𝗮𝗿𝗸𝗲𝘁 𝗥𝗲𝗰𝗮𝗽: 𝗟𝗶𝗾𝘂𝗶𝗱𝗶𝘁𝘆 𝗥𝗼𝘁𝗮𝘁𝗶𝗼𝗻𝘀 𝗮𝗻𝗱 𝘁𝗵𝗲 𝗙𝘂𝗻𝗱𝗮𝗺𝗲𝗻𝘁𝗮𝗹 𝗗𝗶𝘀𝗰𝗼𝗻𝗻𝗲𝗰𝘁
The past week delivered a textbook example of institutional de-risking. A confluence of geopolitical friction and extended valuations triggered a violent rotation out of mega-cap technology and into historically underperforming sectors.
𝟭. 𝗧𝗵𝗲 𝗠𝗮𝗰𝗿𝗼 𝗠𝗲𝗰𝗵𝗮𝗻𝗶𝗰𝘀
Capital is not leaving the market; it is reorganizing. When institutional funds face rising macro uncertainty, they mechanically trim their most profitable positions to raise cash or reallocate into lower-beta assets. This liquidity event disproportionately hit the semiconductor and compute layers. The $NSDQ100 absorbed a -4.26% drawdown this week, while the $SPX500 saw a milder -1.64% contraction. This divergence confirms a deliberate tech-focused rotation rather than a systemic economic failure.
𝟮. 𝗧𝗵𝗲 𝗘𝗮𝗿𝗻𝗶𝗻𝗴𝘀 𝗗𝗶𝘀𝗰𝗼𝗻𝗻𝗲𝗰𝘁
During liquidity events, price action temporarily divorces from structural reality. $ASML released Q2 earnings that confirmed the strict mathematical necessity of their physical monopoly. They raised forward guidance and demonstrated accelerated installed base management. Yet, the stock was sold off alongside speculative software.
The underlying math remains unchanged. The hyperscalers are locked in a multi-trillion-dollar capital expenditure race. They cannot pause their orders for advanced lithography or high-bandwidth memory. The physical chokepoints of the digital economy continue to command absolute pricing power, even as short-term algorithms force liquidation.
𝟯. 𝗣𝗼𝗿𝘁𝗳𝗼𝗹𝗶𝗼 𝗣𝗲𝗿𝗳𝗼𝗿𝗺𝗮𝗻𝗰𝗲 𝗮𝗻𝗱 𝗦𝘁𝗿𝗮𝘁𝗲𝗴𝗶𝗰 𝗔𝗹𝗶𝗴𝗻𝗺𝗲𝗻𝘁
Our strategy inherently accepts short-term volatility as the specific price for long-term alpha. Because we deliberately concentrate capital in the structural monopolies driving this physical infrastructure build-out—such as ASML, $NVDA, and $MU—our portfolio absorbed a -7.38% hit this week.
This drawdown is a statistical feature of our high-conviction positioning, not a flaw in the thesis. Zooming out, the Year-to-Date (YTD) data validates our strict supply chain concentration against the benchmarks:
• $SPX500 YTD: +𝟴.𝟴𝟱%
• $NSDQ100 YTD: +𝟭𝟯.𝟮𝟴%
• 𝗢𝘂𝗿 𝗣𝗼𝗿𝘁𝗳𝗼𝗹𝗶𝗼 𝗬𝗧𝗗: +𝟭𝟱.𝟭𝟲%
We do not chase broad market beta. We own the supply chain bottlenecks. The fundamental demand for computing infrastructure remains absolute, and we hold the line.
#MarketRecap #TechRotation #MacroStrategy #Semiconductors #StructuralMonopolies