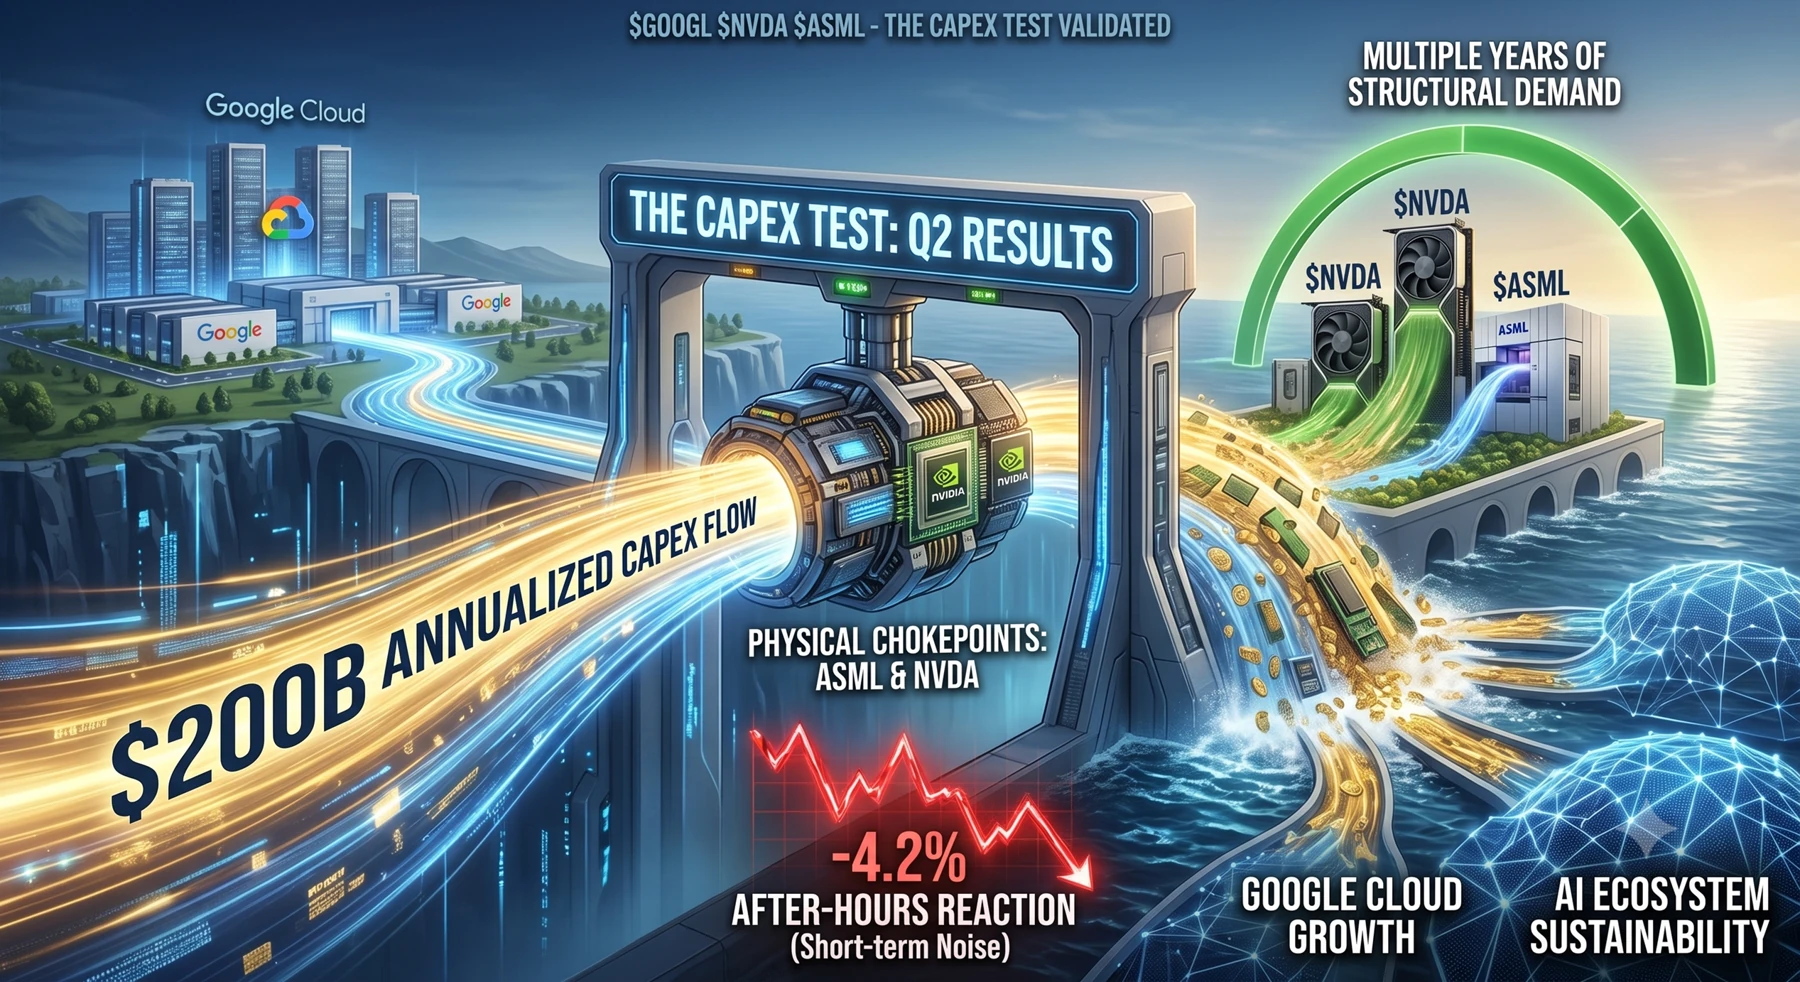
📊 𝗔𝗹𝗽𝗵𝗮𝗯𝗲𝘁 ($𝗚𝗢𝗢𝗚𝗟) 𝗤𝟮 '𝟮𝟲: 𝗧𝗵𝗲 𝗖𝗔𝗣𝗘𝗫 𝗙𝗹𝗼𝘄 𝗖𝗼𝗻𝗳𝗶𝗿𝗺𝘀 𝗼𝘂𝗿 𝗖𝗵𝗼𝗸𝗲𝗽𝗼𝗶𝗻𝘁 𝗧𝗵𝗲𝘀𝗶𝘀
Alphabet’s Q2 2026 results, released after the close, provide definitive mathematical validation for our core investment philosophy: *The Economics of Chokepoints.*
Retail participants are currently reacting to short-term advertising noise and CAPEX-induced margin pressure, causing a superficial -4.2% drop in after-hours trading. Professionals, however, are parsing the data to confirm the velocity of the digital industrial revolution.
Here is a strictly analytical synthesis of the results and their implication for our portfolio.
𝟭. 𝗧𝗵𝗲 𝗤𝟮 𝟮𝟬𝟮𝟲 𝗗𝗮𝘁𝗮
Alphabet delivered its 12th consecutive quarter of double-digit revenue growth.
• Total Revenue: $119.8 billion (up 24% YoY), beating estimates.
• EPS: $9.11 (up 294% YoY), driven by exceptional operating leverage.
• Google Cloud: Stands out. Revenue $24.8 billion (up 82% YoY), with operating income of $8.8 billion—more than tripling from a year ago.
• 𝗖𝗔𝗣𝗘𝗫 (𝗧𝗵𝗲 𝗦𝗶𝗹𝗶𝗰𝗼𝗻 𝗧𝗼𝗹𝗹): $44.9 billion for the quarter. Crucially, management raised its full-year 2026 CAPEX guidance to $195–$205 billion and signaled significant increases for 2027.
𝟮. 𝗛𝗼𝘄 𝘁𝗵𝗶𝘀 𝗩𝗮𝗹𝗶𝗱𝗮𝘁𝗲𝘀 𝗬𝗲𝘀𝘁𝗲𝗿𝗱𝗮𝘆'𝘀 𝗔𝗻𝗮𝗹𝘆𝘀𝗶𝘀
Yesterday, we framed Alphabet's earnings as "The CAPEX Test." The data released today confirms Google is passing this test by sacrificing short-term free cash flow ($ -5.9 billion this quarter) to secure long-term compute dominance.
When $GOOGL (Alphabet Inc Class A) commits $200 billion to foundational infrastructure, that money does not evaporate. It flows up the food chain, directly on to the top line of the structural monopolies we concentrate capital in, such as $NVDA (NVIDIA Corporation) and $ASML (ASML Holding NV). Alphabet confirms it must keep spending to relieve compute constraints for its $514 billion Cloud backlog. We own the entities dictating the terms of that spend.
𝟯. 𝗟𝗼𝗼𝗸𝗶𝗻𝗴 𝗔𝗵𝗲𝗮𝗱 & 𝗣𝗼𝗿𝘁𝗳𝗼𝗹𝗶𝗼 𝗢𝘂𝘁𝗹𝗼𝗼𝗸
The message is clear: The trillion-dollar CAPEX arms race among hyperscalers is not slowing; it is accelerating. This report guarantees multiple years of structural demand for the physical bottlenecks making this build-out possible.
While broad indices like the $SPX500 handle the margin compression of mature software business model transition, our portfolio isolates the physical chokepoints that command absolute pricing power. Short-term volatility from after-hours algorithms creates mispricing, not flaw in the thesis.
We demand mathematical certainty, and the data from this report confirms we hold the supply chain monopolies.
Review my complete portfolio structure and historical performance directly on my profile.